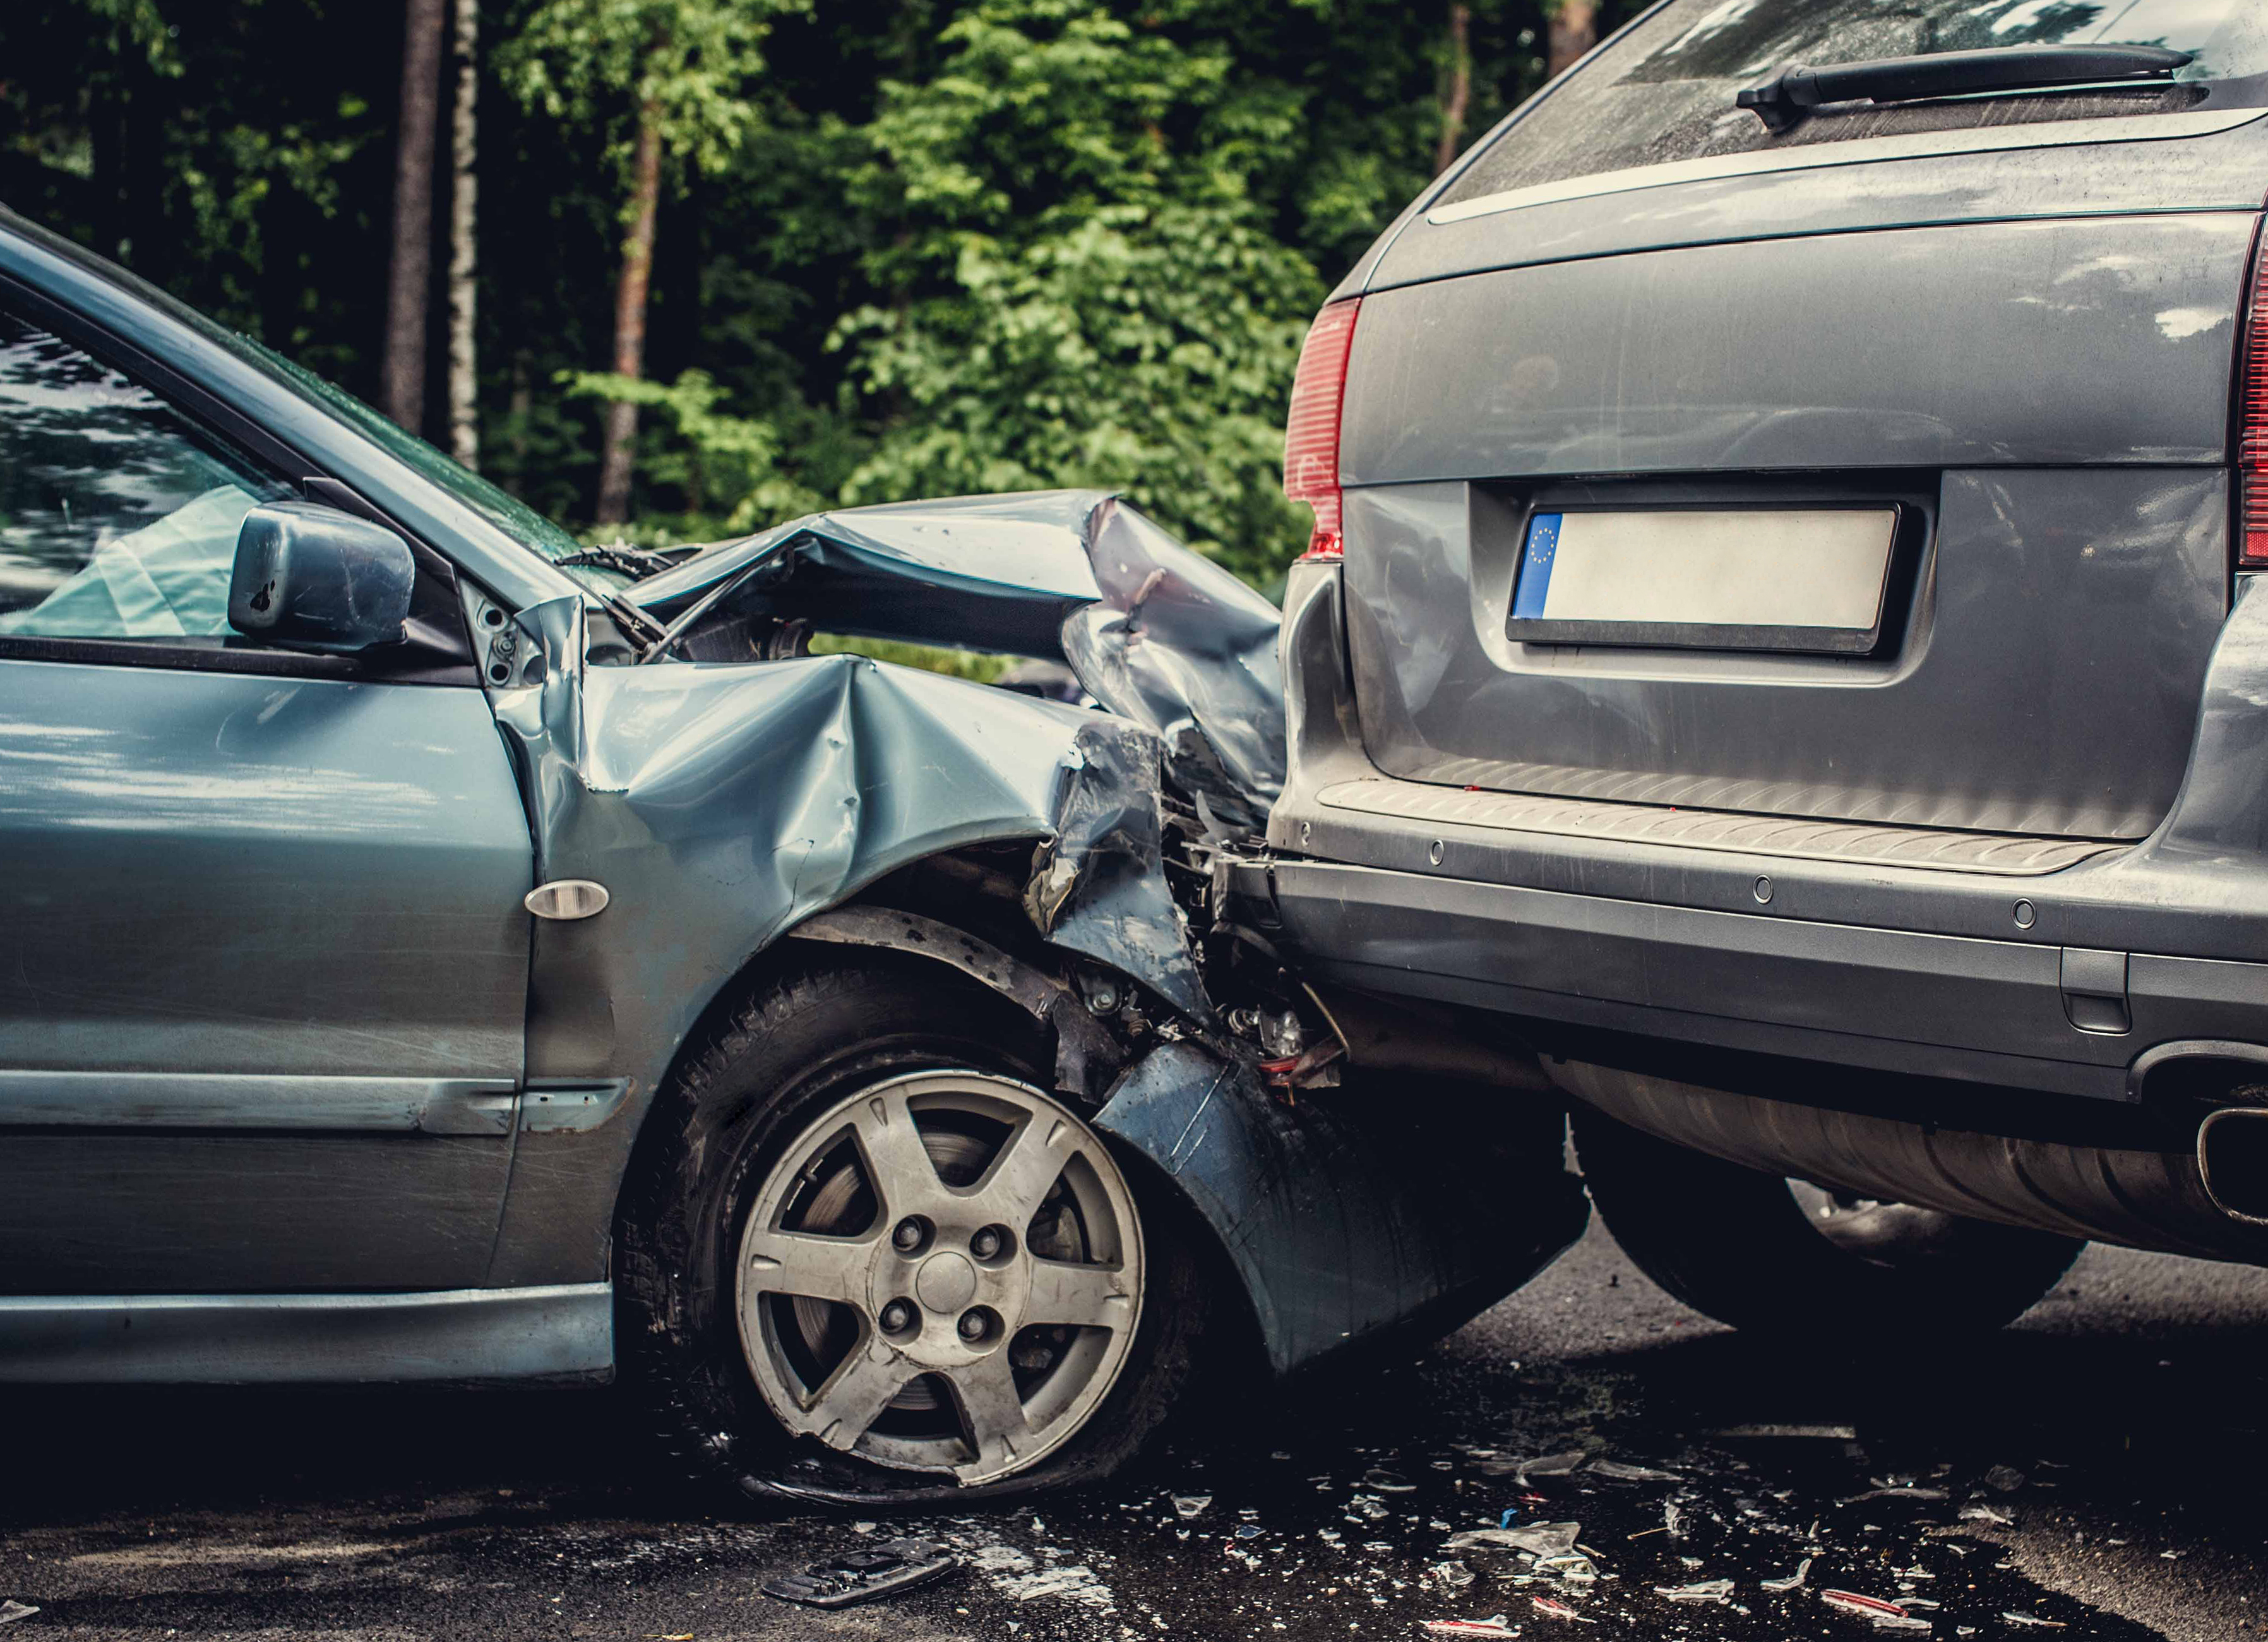
Steps to Take After an Accident with an Uninsured Driver
Getting into a car accident is stressful under any circumstances, but the situation becomes even more overwhelming when the other driver has no insurance. Even though most states require drivers to carry minimum liability coverage, a surprising number of people still get behind the wheel without it. When that happens, securing compensation for injuries, lost income, or vehicle damage becomes more complicated. Still, you have several avenues to pursue financial recovery.
Immediate Actions to Protect Yourself
Right after the accident, what you do next can significantly influence the outcome of your claim. First, check yourself and any passengers for injuries. If anyone is hurt, call for medical assistance immediately. Even if the injuries seem minor, it’s important to get evaluated.
Next, contact law enforcement so a formal accident report can be filed. This document will be important for your insurance claim and any future legal steps you may need to take. Gather as much evidence at the scene as possible. Collect the other driver’s contact information, details about the vehicles involved, and photographs of the damage, roadway, and overall crash site. These details help create a clear record of what happened.
Once you’re safe and have spoken with the police, notify your insurance company as soon as possible. Reporting the accident promptly allows the claims process to begin and ensures you don’t miss any deadlines. Because most states follow an “at-fault” model—meaning the responsible driver must pay for damages—the ultimate resolution will depend on who is determined to have caused the crash.
How Your Insurance May Help
If the uninsured driver is found to be at fault, your insurance policy may provide coverage depending on the protections you have in place. Many people carry uninsured or underinsured motorist coverage (often called UM/UIM). This type of insurance is designed specifically for scenarios like this. It may cover your medical expenses, lost earnings, and sometimes damage to your vehicle when the person responsible for the accident has little or no insurance.
If you also have optional protections such as collision coverage, your insurer may help pay for repairs to your vehicle regardless of who caused the crash. Personal injury protection (PIP), which is required or offered in many states, can also help cover medical bills and sometimes lost wages without needing to prove fault. Without these types of coverage, however, your options for compensation through insurance may be more limited.
Considering Legal Action
When insurance isn’t enough—or when you lack certain coverages—you may decide to pursue a lawsuit against the uninsured driver. Taking legal action can potentially help you recover expenses such as medical treatment costs, repair bills, and compensation for pain and suffering. Before choosing this route, it’s important to consider the driver’s financial situation. Even if you win a judgment, it may be difficult to collect payment if the individual doesn’t have adequate income or assets.
Because these cases can be complex, consulting with a skilled car accident attorney can be beneficial. An attorney can help you evaluate the driver’s ability to pay, assess the strength of your case, and advise you on the best steps for documenting your losses. They can also guide you through the legal and insurance processes, making sure you understand your rights and obligations along the way.
Special Considerations for Hit-and-Run Accidents
Hit-and-run collisions often fall under the same coverage rules as accidents caused by uninsured drivers. Since the at-fault driver is unknown or cannot be located, uninsured motorist coverage typically applies. As with any accident, file a police report immediately and notify your insurance carrier right away. The more documentation you can provide about the incident, the smoother the claims process will be.
Why Acting Quickly Matters
Accidents involving uninsured drivers can feel discouraging and complicated, but taking swift action is the best way to protect your financial wellbeing. Promptly reporting the crash, gathering evidence, and understanding your coverage are essential steps. If you choose to work with legal counsel, they can help you navigate insurance negotiations, explain state-specific rules, and advocate on your behalf.
Although dealing with an uninsured driver may create extra obstacles, you have resources available to help you recover. By staying informed, documenting everything thoroughly, and using the coverages you have, you can reduce financial stress and move forward with confidence.